
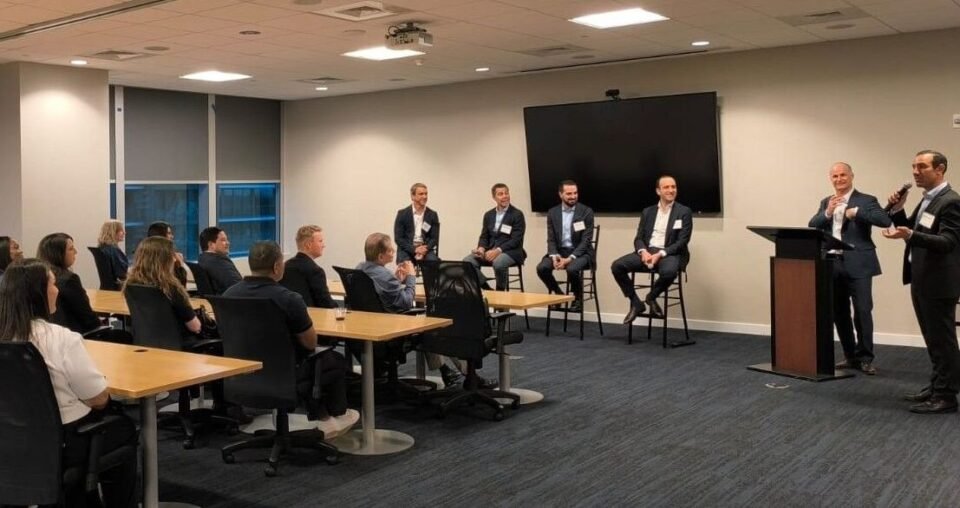
Echoing what already appears to be a long-term structural trend, Latin American investors and the region’s investment industry are increasingly hungry for alternative assets. Driven by a variety of factors, this phenomenon has not gone unnoticed in Miami, the heart of Latin American offshore investments. Unsurprisingly, the Florida chapter of the CAIA Association—which groups investment professionals holding the CAIA alternative investment designation—dedicated its latest panel to this topic.
The session, titled “Capital Without Borders,” brought together a variety of figures, presenting perspectives from family offices and specialized GPs on the future of this market in the region. In that discussion, a key driver was the growing sophistication of investors in the region and the tailwinds presented by various pools of capital.
“What is interesting about LatAm right now is that family offices and institutional investors have truly grown over the last decade, becoming more institutionalized,” indicated Hernan van Waveren, CIO of Grupo Werthein Family Office. Added to this is that the region has become a greater source of investment opportunities for private markets.
From the perspective of global firms, the neighborhood offers a compelling story. Jordie Olivella, Managing Director at KKR—who represents the firm in both Latin America and Canada—describes three attractive aspects: market size, which BCG places at around 8.7 trillion dollars; a shift in the political climate toward a more investment-friendly environment; and a global macroeconomic and commodities backdrop that favors wealth creation in the region.
As alternatives have gained prominence in regional portfolios, the professionals who have certified with CAIA have grown alongside them. From 326 members about four years ago, they now reach 600 professionals, with Brazil as the primary market, followed by Mexico, Chile, Peru, and Colombia.
Matured Supply and Demand
One of the main drivers behind the surge in demand, as reported by the professionals brought together by CAIA, has been the growing sophistication of Latin American clients. In the past, only a few entities—mainly large institutionals—had knowledge of alternatives and access to private markets. Today, the investor universe is more demanding.
This greater sophistication, highlights Juan José Daboub, CIO at Masala Capital, has led to a different perspective on incorporating alternatives into portfolios. “We used to think of allocators as people seeking access to certain funds, and that it was all about the product. Now, in what we can call an allocator 2.0, it is about seeing how products fit into my broader portfolio,” he explained.
Olivella agrees with the assessment, outlining a new orientation toward portfolio optimization. “What is happening is that the level of the game has been raised for both GPs and LPs,” he commented, describing managers as portfolio “architects.” And these professionals are assembling portfolios using various structures, he noted, including primary strategies, secondaries, co-investments, and semi-liquids.
On the other side of the coin, supply has also been evolving in lockstep with the development of the industry’s investment capabilities. “We are absolutely finding more opportunities to invest and more partners to invest directly in the Latin American market,” pointed out Van Waveren of Grupo Werthein.
One of these transformations on the vehicle side is the rise of co-investments. More sophisticated clients, explained David Lopez, Head of LatAm at Thoma Bravo, are turning to this type of investment due to the cost efficiency it offers. “For better or worse, clients have been focusing on co-investments to reduce fees and try to achieve better returns,” he said.
Institutional and Family Office Flows
For the first time, described the Thoma Bravo executive, both engines are firing at once. “This means that institutional capital has been driven by pension fund industry regulation, and, in addition, we are finally seeing access at scale in the wealth segment,” he commented during the panel held in Miami.
On the institutional side, there are several instances where pension funds could demand more alternative assets. Mexico, for example, has a 500-billion-dollar industry growing at 20% a year, while Chile increased contributions in its latest reform and raised investment limits for alternatives. Furthermore, new investors are joining, such as pension vehicles in El Salvador and Costa Rica.
In addition, single family offices—which operate increasingly like institutionals rather than single-client private banks—are also ramping up their appetite. Although this segment has been investing in the asset class for decades, industry figures see room for growth. While FOs currently invest around 30% of their capital in alternatives, that figure could reach the 40% registered in the US, according to López.
The phenomenon of a holistic portfolio view becomes especially relevant for this segment, as emphasized by Daboub of Masala. “Most of these families already have a very concentrated private equity position, which is their own operating business,” he explained, adding that this has become another piece of portfolio diversification, as they must find “an alternative to the exposure they already hold.”
“Before, they looked for what was available, whereas now they look for what they can buy that is uncorrelated with what they own,” he indicated, “what will give them an additional return over what they can find locally or in public markets.”
The Emerging Wealth Segment
A few rungs down the private wealth scale, a segment gaining prominence in the region—and inspiring the creation of a variety of wealth management firms—is private wealth clients.
This, industry players stress, is also a trend echoing a global phenomenon. “The same trends seen in the US are playing out in Latin America,” said Olivella of KKR. “Major private banks, wirehouse channels, RIAs, and independent broker-dealers now have access to high-quality products from solid GPs,” he added. In that vein, the executive underlined the role that the development of evergreen vehicles played in this dynamic.
Although the most cited figure is a 2% penetration rate in Latin American wealth management channels, noted the professional, this average hides a heterogeneous landscape combining highly sophisticated investors, with 15% to 20% allocations in alternatives, and clients who have not yet entered the space.
Overall, these flows have left a mark on the industry, not only in the work of international giants like JPMorgan or Morgan Stanley, but also in the expansion of major Latin American financial groups such as Itaú, Credicorp, SURA, and BTG Pactual.
Looking ahead, the industry views mass-affluent clients as the next frontier. “There is a lot of interest and capital flowing from the Ultra High Net Worth segment, and I think the next wave will be the affluent channel,” said López of Thoma Bravo.
For the professional, this will nevertheless require the use of local structures, but he foresees “a massive opportunity for private wealth in private markets over the next five years.”