
Family offices are increasingly turning to alternative credit for income, diversification and potential downside protection, but allocations can be less diversified than they appear. In this article for IFA Magazine, Rémi Casals, Head of International Wealth Solutions at First Eagle Investments, explores how a broader approach to alternative credit could help family offices access a wider range of return drivers, and offers advisers insight into the different strategies and risks to consider when assessing this increasingly important part of the investment landscape.
For many, this has increasingly included allocations to alternative investments, which can help provide institutional investors differentiated sources of return as a complement to more traditional equity and fixed income allocations.
Family offices occupy a distinctive niche within the investment ecosystem, controlling institutional-sized assets but with needs often more akin to those of individual investors.
While every family office has unique circumstances, needs and objectives, they share several commonalities that shape their investment philosophies, including an emphasis on capital preservation and growth, an absolute-return mindset, a focus on alignment and long-term orientation.
In recent years, family offices have increasingly embraced alternative credit as a tool to execute their philosophies, not surprising given the patient capital that family offices represent.
That said, we find that the alternative credit allocations typical of family offices today are often less diversified, less flexible and more directionally exposed than they seem on the surface, undermining the benefits of exposure to the asset class.
Mezzanine and equity tranches provide access to potential opportunities created by market dislocations, technical selling pressure and structural complexity, with returns derived from income and the potential for favourable asymmetry
In a market environment that may seem particularly complex, family offices have several factors working in their favour. Not the least of which is potential access to sophisticated, institutional-quality investment solutions. For many, this has increasingly included allocations to alternative investments, which can help provide family offices differentiated sources of returns as a complement to more traditional equity and fixed income allocations.
While alternative investments in aggregate comprise a meaningful portion of a typical family office portfolio, allocations to private credit, at 4%, have remained modest despite the expectation that the asset class will continue its rapid expansion[1]. Industry forecasts project private credit assets under management could reach approximately $4.5 trillion by 2030[2].
While a larger number of family offices appear to be embracing alternative credit exposure, our experience has been that allocations tend to follow a fairly consistent pattern – a core allocation to direct lending complemented by opportunistic or special-situations strategies and often some exposure to real estate credit. While such an allocation may appear diversified on the surface, looking at how these investments have behaved over time suggests otherwise:
First, in these portfolios, the relationship between prices and yields often curves in an unfavourable way. In an environment of tight credit spreads, such negative convexity implies limited upside potential combined with amplified downside risk, particularly in stress scenarios.
Second, many portfolios are underpinned by the same core drivers of performance, such as corporate earnings, leverage and refinancing conditions, and truly differentiated sources of return can be lacking.
Third, alternative credit portfolios are often bulleted to match a known future liability. As a result, returns are dependent on fixed maturities and repayment events, which ties capital to refinancing cycles and limits flexibility, particularly during periods of market dislocation.
In short, a family office’s alternative credit allocation may be less diversified, less flexible and more directionally exposed than it seems.
How private credit components work together to diversify and generate returns
The evolution of alternative credit has broadened the investment opportunity set beyond traditional corporate lending and direct lending strategies. As investors seek more diversified sources of income and return, certain segments of public and private credit markets stand out for their ability to provide exposure to distinct risk factors, structural protections and return drivers that are less dependent on economic growth or spread compression.
Many of these opportunities exist in areas where capital remains constrained by regulatory requirements, market complexity, specialized expertise or investor behaviour. As a result, investors may be able to access durable sources of risk premia that are supported by collateral, contractual cash flows and structural protections rather than relying solely on corporate credit fundamentals.
Three areas are particularly notable within this opportunity set:
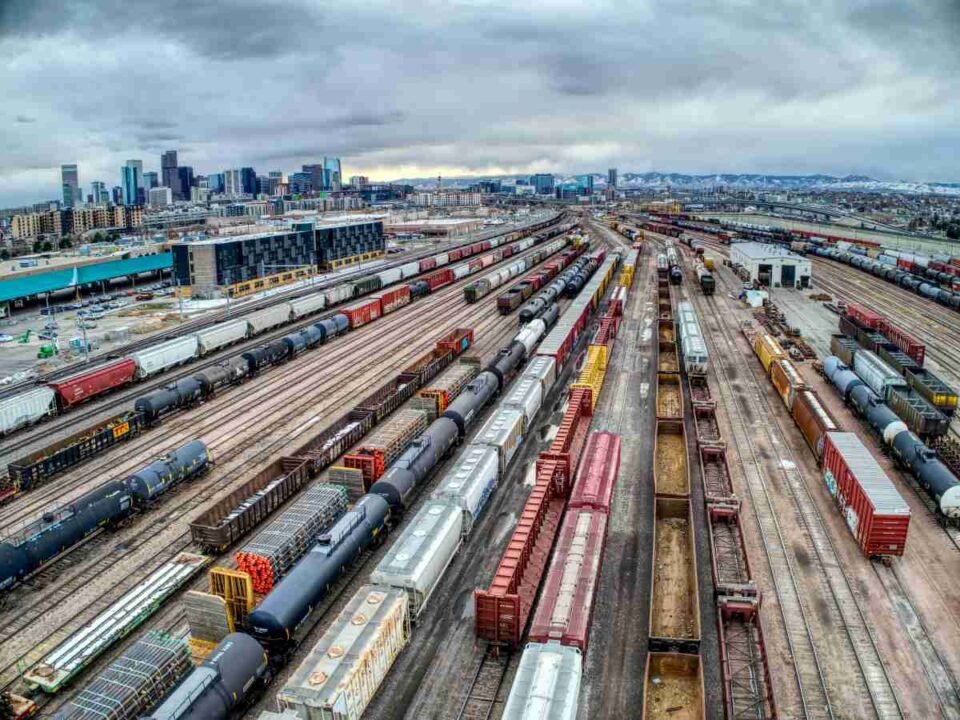
- Real assets. Asset-based financing linked to essential transportation and infrastructure assets, such as railcars, offers exposure to long-lived assets with contractual cash flows. Railcar leasing can provide an income profile similar to investment grade fixed income, alongside private equity-like return potential.
- Structured credit. Mezzanine and equity tranches provide access to potential opportunities created by market dislocations, technical selling pressure and structural complexity, with returns derived from income and favourable asymmetry. Lower middle-market direct lending remains attractive, with wider spreads, more conservative leverage and greater diversification.
- Private asset-based lending. Residential lending, specialty finance and corporate asset-based lending use specific collateral pools and cash-flow streams to create differentiated returns and provide downside mitigation.
These potential opportunities illustrate how alternative credit has evolved beyond traditional spread-based investing, offering investors greater access to a broader set of return drivers, income sources and portfolio diversification benefits across market environments.
[1] With Intelligence; data as of May 28, 2025.
[2] PitchBook; data as of March 12, 2025.