
The long-term return outlook for investors has improved due to stronger corporate earnings, higher bond yields and greater dispersion for hedge funds to capture alpha.
This is according to JP Morgan Asset Management’s 2027 Long-Term Capital Market Assumptions (LTCMA), which upgraded its forecasted returns for a 60/40 stock-bond portfolio over the next 10–15 years to 7%.
In its long-term projections, the firm said that for investors who embrace up to 30% in diversified alternatives, the projected return increases to 7.5% and the Sharpe ratio increases by 21%.
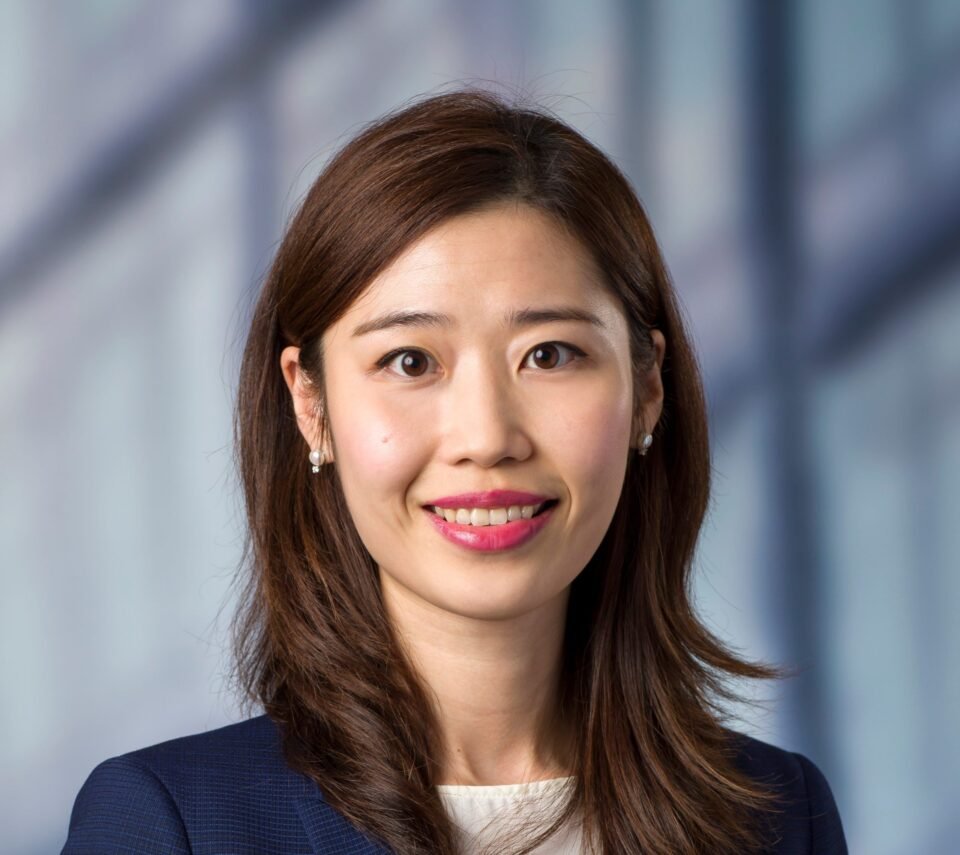
Sylvia Sheng (main picture), lead portfolio manager of multi-asset solutions Asia, J.P. Morgan Asset Management said: “With inflation volatility remaining elevated and stock-bond correlations becoming less reliable, investors may need to look beyond traditional diversification.”
JPMAM’s report also expects higher inflation volatility, ongoing currency debasement and “growing opportunities to capture active alpha” in the long run, and pointed to alternatives as “essential”.
It upgraded its long-term outlook for returns from diversified hedge funds by 1.4%, based on “sustained alpha trends” and higher rates.
“We’re expecting more dislocation, more dispersion across markets and within markets, and that’s really a more of a rich environment for diversified hedge funds to capture,” Sheng said at a media briefing discussing the findings.
The findings are particularly relevant for J.P. Morgan’s private bank clients, who still have a lot of uninvested cash on the sidelines, according to Ulysses Lau, Asia head of investments and engagement, J.P. Morgan private bank.
He said: “The case for alternatives has never been stronger; they can broaden sources of return and help diversify risks that stocks and bonds alone may not fully address.”
“Beginning in Asia this year, we’re evolving how clients access and manage alternatives through a personalised, advice-led approach.”
“By considering each client’s goals, risk tolerance and liquidity needs, we can integrate alternatives more thoughtfully into their broader portfolio and long-term plan.”
Lau suggested that clients with a long-term time horizon, higher risk tolerance and no liquidity needs can enhance returns with 30% allocated to private investments.
Higher returns ahead
Aside from a better outlook for alternatives, JPMAM also expects developed market equity returns to outpace emerging market equity returns for the first time in decades.
It said the run up in Taiwanese and Korean semiconductor stocks prompted the firm to lower its long-term return outlook for the wider emerging market equity asset class.
It expects a global investment surge centred around AI and lasting for another 15 years, to boost total factor productivity by 50% and push US real GDP growth to 2.1% and developed world nominal growth up to 4.2%.
The firm also forecasts profit margins of over 15% to push the returns from US large cap equity to 7.5%, leading to developed market equity projections overtaking emerging markets for the first time in the publication’s history.
Higher real yields will also drive global aggregate bond returns to 5.3%, the highest in two decades, up from a low of 2.1% in 2021, according to the report.
For Asia ex-Japan equities, the report expects a 7.1% return, with Japanese equities projected at 9.1%, Chinese domestic equities at 7.4% and Hong Kong equities at 6.9%.