
TradingKey – In August, gold (XAUUSD) prices continued to rebound from near $4,000 and once approached $4,700. As the key resistance level of $4,500 was broken, technical analysis shows that gold prices have opened up upside potential toward $4,900, with gold expected to return to a bull market trend and the precious metals market regaining investor attention. If gold re-enters a medium- to long-term upward cycle, besides direct investment in gold and gold ETFs, gold mining stocks may offer greater earnings leverage than gold prices themselves.
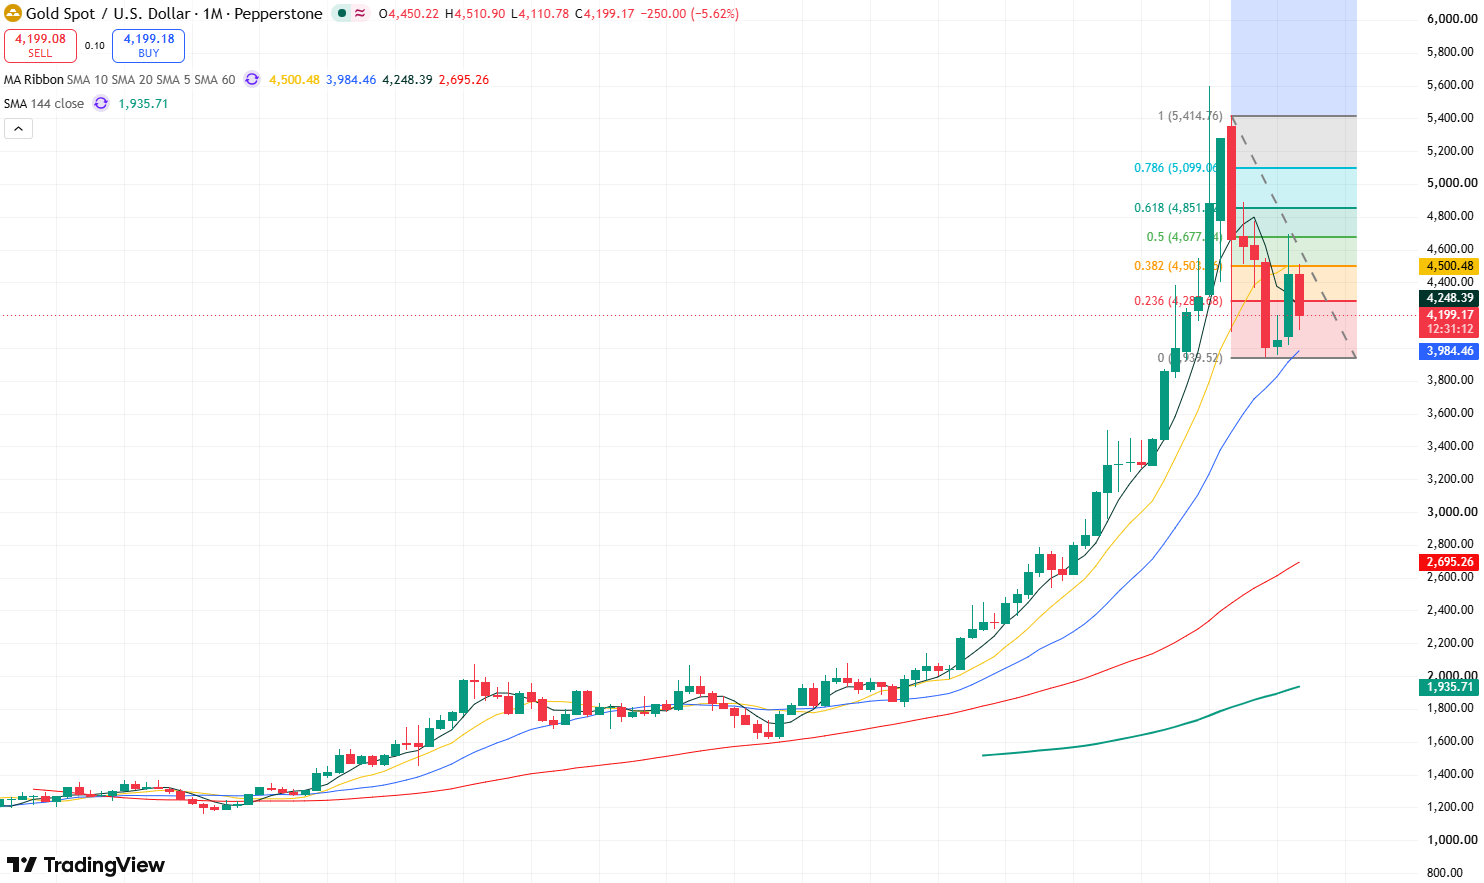
Gold price monthly chart, Source: TradingView
For gold miners, corporate profits mainly stem from gold selling prices minus production costs. When the growth rate of gold prices significantly outpaces that of mining costs, the profit miners earn per ounce of gold produced expands rapidly. Therefore, in a gold bull market, what is truly worth looking for is not merely the companies with the highest production, but those with lower production costs, high-quality mines, strong cash flow, and stable balance sheets.
Following this logic, within the U.S. precious metals sector, Newmont (NEM), Agnico Eagle Mines (AEM), and Wheaton Precious Metals (WPM) represent three investment directions: high gold price leverage, high quality with low costs, and asset-light models, respectively.
Newmont: One of the World’s Largest Gold Miners, Production Scale Brings Higher Profit Elasticity
Newmont is one of the world’s largest gold producers, with a 2026 gold production target of approximately 5.26 million ounces and AISC guidance of around $1,680 per ounce. Its massive gold production means that for every given increase in gold prices, the absolute impact on the company’s revenue and free cash flow is highly significant.
According to its latest financial report, elevated gold prices have already begun to reflect in cash flow. The company produced approximately 1.3 million ounces of gold in the second quarter and generated about $2.2 billion in free cash flow. Meanwhile, Newmont authorized a $6 billion share buyback program and maintained an annual cash dividend framework of around $1.1 billion.
Therefore, if investors are seeking a leading gold stock that is highly correlated with gold prices, large in scale, and strong in cash flow generation, NEM is a highly representative choice. Key risks stem from mine operations, rising energy costs, and a sharp pullback in gold prices.
Agnico Eagle: Low Costs, Low Debt, Quality Asset Among Gold Miners
AEM’s greatest strength lies in its cost control and outstanding balance sheet quality.
The company’s 2026 gold production is expected to be approximately 3.3 million to 3.5 million ounces, with AISC guidance of around $1,400 to $1,550 per ounce. Actual Q2 AISC was about $1,459 per ounce, significantly lower than the realized gold price of around $4,483 per ounce during the same period, allowing the company to generate a record quarterly free cash flow of approximately $1.335 billion.
Another advantage of AEM is its balance sheet. As of the end of the second quarter of 2026, the company held approximately $3.464 billion in cash, with net cash reaching about $3.267 billion, while total debt was only around $197 million. Strong cash reserves mean the company maintains robust capacity for capital expenditures and shareholder returns even amid gold price volatility.
For gold stocks, while rising gold prices are indeed important, what truly determines earnings elasticity is often whether costs can be controlled. When gold prices rise, lower costs amplify profits; when gold prices fall, low costs and low debt enhance the company’s counter-cyclical resilience.
Therefore, if investors seek a long-term allocation to gold mining stocks rather than chasing maximum short-term gold price elasticity, AEM is highly representative.
Wheaton Precious Metals (WPM): Low-Cost Access to Gold and Silver, Margin Advantage Stands Out Amid High Gold Prices
Unlike traditional gold miners, WPM primarily operates under a precious metals streaming model: providing upfront capital to mining companies in exchange for the right to purchase a portion of future gold, silver, and other metal production at a predetermined price.
This business model means that WPM does not directly bear most of a mine’s labor, energy, and equipment costs, making it less sensitive to mining cost inflation compared to traditional miners.
WPM currently holds streaming and royalty agreements covering 22 operating mines, 20 development projects, and 15 exploration and other-stage projects. The company expects its gold equivalent production to reach approximately 860,000 to 940,000 ounces in 2026 and projects it to increase to about 1.2 million ounces by 2030, an increase of roughly 50% from 2026 levels.
As precious metal prices rise, the company’s cash flow has also improved significantly. In the second quarter of 2026, WPM achieved record revenue of approximately $929 million, net income of $543 million, and operating cash flow of $650 million.
WPM’s key feature is its dual exposure to both gold and silver, paired with a relatively asset-light operating model. Therefore, for investors looking to participate in the precious metals bull market while mitigating traditional mining cost and operational risks, WPM is a noteworthy alternative.
Summary
If gold re-enters a medium-to-long-term bull market, these three companies effectively represent three distinct investment approaches.
For investors who expect gold to continue rising sharply and seek greater sensitivity to gold prices, Newmont is a key focus. Its massive gold production means higher gold prices can rapidly translate into cash flow, though investors must also assume higher mine operational and cost risks.
Investors who prioritize corporate quality and long-term holding can focus on AEM. A lower AISC, robust free cash flow, and a net-cash balance sheet give the company strong profitability when gold prices rise, while providing better defensiveness when gold prices pull back.
Those looking to mitigate traditional mining risks while gaining exposure to both gold and silver may look into WPM. Its streaming model enables it to benefit from rising precious metals prices without directly assuming most mine operational costs.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Disclaimer: The content of this article solely represents the author’s personal opinions and does not reflect the official stance of Tradingkey. It should not be considered as investment advice. The article is intended for reference purposes only, and readers should not base any investment decisions solely on its content. Tradingkey bears no responsibility for any trading outcomes resulting from reliance on this article. Furthermore, Tradingkey cannot guarantee the accuracy of the article’s content. Before making any investment decisions, it is advisable to consult an independent financial advisor to fully understand the associated risks.