
Innovative Industrial Properties has seen its share price fall 62.1% over the past 5 years, even though the stock is up modestly so far in 2026. That kind of long term setback raises a clear question for investors who still follow Innovative Industrial Properties today, which is whether the current valuation can be explained by its earnings power.
- A 62.1% decline over 5 years puts the focus squarely on whether the market now views the stock’s earnings as structurally less valuable than before.
- The business model, which relies on real estate income tied to a specialized tenant base, can have a direct impact on how durable its profit stream looks and how investors weigh that against the current share price.
- Your read on Innovative Industrial Properties is one view; the desks covering it have another. See what analysts think Innovative Industrial Properties’s shares could be worth.
The stock’s next move may depend on whether its current earnings profile justifies where Innovative Industrial Properties is trading today.
If you are weighing whether Innovative Industrial Properties’ earnings justify today’s price, it can help to compare that same question across 34 high quality undervalued stocks.
Does Innovative Industrial Properties Look Undervalued on Earnings?
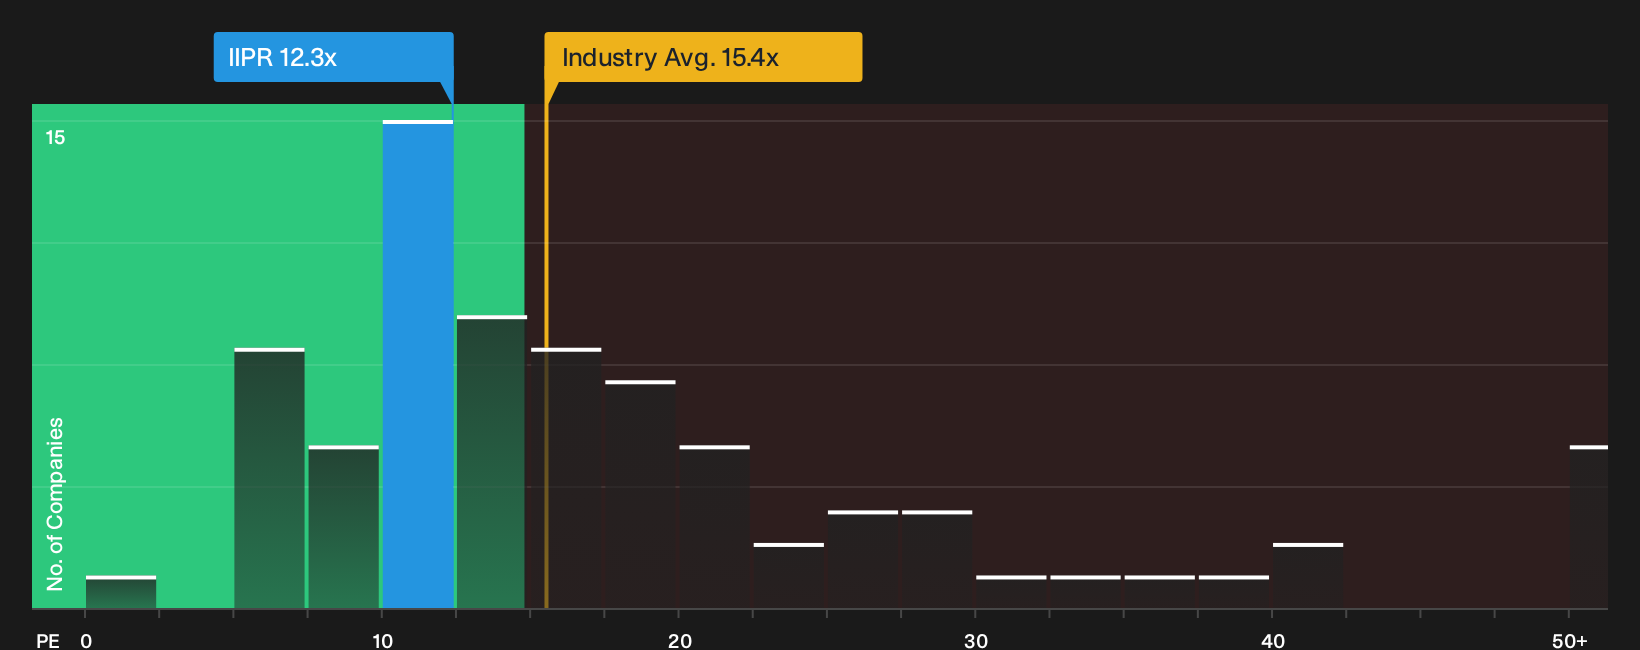
The P/E ratio fits Innovative Industrial Properties because earnings are central to how investors judge a real estate income vehicle. Right now the stock trades on a P/E of about 12.3x, which is lower than the Industrial REITs group on roughly 15.4x and well below the broader peer set at around 29.6x. That gap indicates the market is assigning a lower price to each dollar of current profit for this business compared with many alternatives in the sector.
A fair P/E for Innovative Industrial Properties, based on factors like its cash generation profile, balance sheet metrics, sector, size and risk mix, could be higher than where the shares trade today. The current 12.3x level sits below that modelled range, so the market is pricing the stock at a discount to what this framework suggests may be justified by its earnings power. Explore the numbers behind Innovative Industrial Properties’s P/E valuation.
The Innovative Industrial Properties Narrative: What Would Justify Today’s Price?
Simply Wall St Narratives pick up where the valuation puzzle for Innovative Industrial Properties leaves off. They spell out the future growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today, and they sit on the platform’s Community page. Each scenario lays out the assumptions behind its view of fair value in a transparent way so you can compare those expectations with the numbers the business actually reports over time.
One of the top community narratives on Innovative Industrial Properties: 9% undervalued
“Regulatory changes and access to cheaper financing for cannabis operators threaten demand for IIPR’s core business model and future revenue growth…”
Discover why this Narrative puts Innovative Industrial Properties at 9% undervalued.
Before you act on Innovative Industrial Properties’ valuation, there is one more piece to check
Price multiples only tell part of the story for Innovative Industrial Properties, and the research has also surfaced specific risk flags that could change how you weigh everything else. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com