
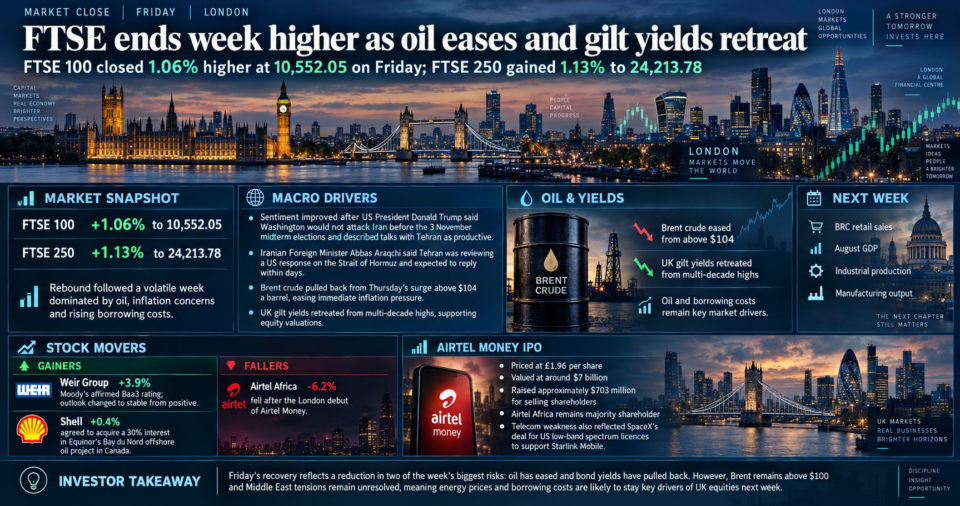
The FTSE 100 closed 1.06% higher at 10,552.05 on Friday, while the FTSE 250 gained 1.13% to 24,213.78.
The rebound followed a volatile week dominated by oil prices, inflation concerns and rising government borrowing costs.
Sentiment improved after US President Donald Trump said Washington would not attack Iran before the 3 November midterm elections, while describing talks with Tehran as productive.
Iranian Foreign Minister Abbas Araqchi said Tehran was reviewing a US response to its proposal concerning the Strait of Hormuz and expected to reply within days.
The diplomatic signals helped pull Brent crude back from Thursday’s surge above $104 a barrel, easing some of the immediate inflation pressure on markets.
UK gilt yields also retreated from the multi-decade highs reached earlier in the week, providing additional support to equity valuations.
Among individual stocks, Airtel Africa fell 6.2% following the London debut of its mobile-money subsidiary.
Airtel Money was priced at £1.96 per share, valuing the business at around $7 billion, and raised approximately $703 million for selling shareholders. Airtel Africa did not sell shares in the offering and remains the majority shareholder.
Airtel Africa’s decline also reflected broader weakness across telecom stocks after SpaceX agreed to acquire a nationwide portfolio of US low-band spectrum licences, strengthening its plans for Starlink Mobile.
Weir Group rose 3.9% after Moody’s affirmed its Baa3 long-term issuer rating and moved the outlook to stable from positive.
The ratings agency said an upgrade could prove difficult unless Weir demonstrates further improvement in leverage and cash-flow metrics.
Shell gained 0.4% after agreeing to acquire a 30% interest in Equinor’s Bay du Nord offshore oil project in Canada.
Equinor will retain a 70% stake and remain operator, with the partners working towards a potential final investment decision in early 2027.
Attention now turns to next week’s UK economic data, including BRC retail sales figures, August GDP, industrial production and manufacturing output.
For investors, Friday’s recovery reflects a reduction in two of the week’s biggest risks: oil has eased and bond yields have pulled back.
However, Brent remains above $100 and Middle East tensions are unresolved, meaning energy prices and borrowing costs are likely to remain important drivers of UK equities next week.

If anyone reads this article found it useful, helpful? Then please subscribe www.share-talk.com or follow SHARE TALK on our Twitter page for future updates.
All information is provided on an as-is basis. Where we allow Bloggers to publish articles on our platform please note these are not our opinions or views and we have no affiliation with the companies mentioned
